Key Takeaways
A new build home loan in NZ works differently from a standard mortgage, because the lender is funding a home that does not exist yet. Understanding how drawdowns, deposits, valuations and the move to long-term lending work will help you plan the build with fewer surprises.
- With a full build contract, the lender usually releases money in stages as the builder reaches agreed milestones.
- Lending for new builds is exempt from the Reserve Bank's LVR and debt-to-income restrictions, although lender criteria still apply.
- Lenders typically want a fixed-price contract, building consent, plans and details of the builder before approving.
- Keep a contingency fund for variations, site surprises and delays.
- Final drawdown and your long-term loan usually depend on a code compliance certificate and a final valuation.
How new build home loans work in NZ
With a standard mortgage, the lender pays the full loan at settlement against a home that already exists. With a new build, the lender is assessing both your finances and a project, so the application includes land details, plans, specifications, the build contract and the expected value of the finished home.
Construction loans and progress payments
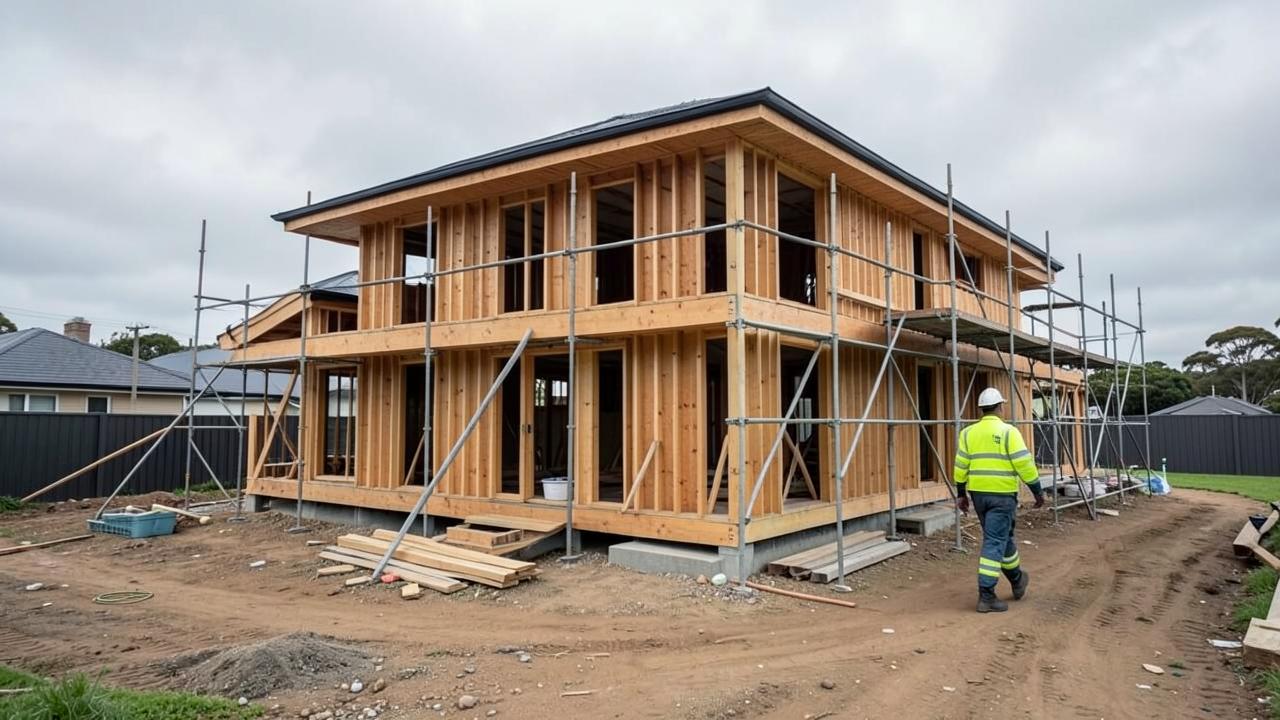
Under a typical build contract, the loan is drawn progressively. The builder issues progress claims as stages are completed, such as foundations, framing, closing in and completion, and the lender releases funds once it is satisfied the stage is done. Many lenders require an inspection or valuer's progress report before each payment.
During the build you usually pay interest only on the amount drawn so far, so your payments rise as more of the loan is used. Once the home is finished, the loan moves to principal and interest repayments.
Turnkey contracts and house-and-land packages
With a turnkey contract, you typically pay a deposit upfront and the balance when the finished home is handed over, so the lending at that stage works much like buying an existing home. House-and-land packages and off-the-plan purchases can be structured either way, depending on the contract. Your lawyer and lender should review the payment schedule before you sign, because it determines how and when the loan is drawn.
Buying the land first
If you are buying a section and building later, the land purchase may be financed separately, often with a larger deposit required for bare land. Ask the lender how the land loan and construction lending will be combined, and when interest and repayments start on each.
Deposits and lending rules for new builds
New builds are treated differently under the Reserve Bank's lending rules, which can make a smaller deposit possible. Your own lender's credit criteria still apply, so the rules widen your options rather than deciding the outcome.
LVR exemption for new builds
Under the Reserve Bank's loan-to-value ratio restrictions, construction loans to build a new home, and loans to buy a newly built home from the developer within six months of completion, are exempt from the high-LVR speed limits. This means some lenders will consider a smaller deposit for a new build than for an existing home. Expect closer scrutiny of the builder, contract and budget in return.
Debt-to-income exemption
The debt-to-income (DTI) restrictions introduced on 1 July 2024 also exempt lending for newly built homes. Lenders must still be satisfied you can afford the repayments under the Credit Contracts and Consumer Finance Act, so your income, spending and existing debts remain central to the application.
Using KiwiSaver for a new build
If you are a first home buyer who has been in KiwiSaver for at least three years, you may be able to withdraw your savings, leaving at least $1,000, to buy land to build on, a house-and-land package or an off-the-plan home. You generally cannot use a first home withdrawal to build if you already own the land. Timing matters, as the withdrawal is paid to your lawyer for settlement, so check the rules for KiwiSaver first home withdrawals early in your planning.
How the lender values your project
Many lenders base the lending on the lower of the total cost (land plus build) and the expected completed value from a registered valuer working from your plans and specifications. If the valuation comes in below cost, you will need to make up the difference from your own funds.
Preparing your finances and your project
A strong application starts well before the first lender conversation. Construction exposes gaps that are less obvious when buying an existing home, so look at your budget, savings and project documents together.
Cost the whole project
Your budget should cover more than the builder's headline price. Include:
- The land, plus legal and survey costs.
- Design, engineering and geotechnical reports.
- Building consent and council fees, including development contributions where they apply.
- Site works such as earthworks, retaining, drainage and service connections.
- Driveways, fencing, landscaping, window coverings and appliances if they are not in the contract.
- Interest during construction and any rent you pay while you wait.
Ask your builder to list exclusions and provisional sums, as these are where costs most often grow.
Set aside a contingency
A contingency fund gives you room to respond when ground conditions differ from expectations, a material costs more than estimated, or the build takes longer. Keep it separate from your deposit and do not count the same savings twice. A project that only works if every estimate is perfect is already under pressure.
Documents lenders usually ask for
- Your income, bank statements, deposit evidence and details of existing debts.
- The signed fixed-price building contract and payment schedule.
- Plans, specifications and building consent.
- Details of the builder, which may include their licensing and any third-party builder's warranty scheme.
- Evidence of contract works insurance during construction.
Most lenders prefer fixed-price contracts with an established builder. Labour-only contracts and owner-builder projects are harder to finance and some lenders will not consider them.
Choosing a lender and loan structure
A lower headline rate is not the only thing that matters with construction lending. How a lender handles progress payments, inspections and variations can affect your build as much as the rate does.
Compare draw policies and fees
Ask how quickly the lender processes progress claims, what evidence it needs and whether inspection or valuation fees apply at each stage. Slow processing can delay payments to your builder. Also ask whether the lender charges for unused approved funds and how variations are handled.
| Loan feature | Question to ask | Why it matters |
|---|---|---|
| Interest during the build | Is interest charged only on the amount drawn, and is it fixed or floating? | Your payments rise as more funds are released. |
| Progress payments | What evidence and inspections are needed before each payment? | Missing paperwork can hold up your builder. |
| Valuations | When are progress and final valuations required, and who pays? | Valuation timing can affect available lending. |
| Variations | How are cost increases approved and funded? | Extra lending needs approval and is not automatic. |
| Completion | What is needed for the final payment and to set up long-term lending? | Delays at the end can push out your move-in date. |
Fixed or floating during construction
Because the balance grows as the build progresses, construction lending is often kept on a floating rate until completion, then restructured into fixed and floating portions. Some lenders allow fixing during the build. Ask how each option works with progress payments.
Test the long-term repayments
Your eventual repayments will be based on the full loan, not the smaller balance drawn early in the build. Use our loan repayment calculator to test the expected balance at a higher rate, and check the result against your real household spending.
Managing the loan during construction
Approval is not the finish line. You will be coordinating progress claims, inspections, invoices and decisions while running your normal finances. One shared record of dates, documents and contacts reduces stress.
Variations and cost overruns
Upgrades to kitchens, flooring, heating or landscaping can add up quickly. Every variation should be in writing with the price and effect on timing. Tell your lender before you commit to a change that alters the approved budget, and do not assume unused approval will cover it: any increase must be agreed by the lender.
Delays and communication
If work stops, the builder changes or the forecast cost rises, contact your lender promptly with the revised programme and updated quotes. A new valuation or affordability check may be needed. If you are renting while you build, allow for the rent running longer than planned.
Your rights as a homeowner
The Building Act gives homeowners specific protections. For residential building work of $30,000 or more including GST, the builder must use a written contract and give you a disclosure statement and consumer checklist before you sign. There is a 12-month defect repair period after completion, and implied warranties allow you to take action for up to 10 years. Building Performance explains these protections in full.
Moving to your long-term mortgage
Start planning the final stage well before practical completion, so missing paperwork does not hold up your final payment or move-in date.
Code compliance and final valuation
Most lenders release the final payment once the council issues a code compliance certificate and a valuer confirms the home is complete. Ask your builder for the expected timing, and make sure records such as producer statements and warranties are handed over.
Restructuring your loan
When the build is complete, your loan moves to principal and interest repayments and is usually restructured into fixed and floating portions. This is a good point to review terms, repayment frequency and how much flexibility you need for extra repayments.
Insurance and investor considerations
Contract works insurance usually covers the build until handover, and lenders require home insurance from the point the completed home becomes their security. Confirm when your home insurance needs to start so there is no gap in cover. If you are building an investment property, interest on residential rental lending is fully deductible from 1 April 2025 under the IRD property rules, and the bright-line test is two years for property sold on or after 1 July 2024. See our investment property lending page and talk to your accountant about your situation.
How SHARE - The Advisory can help
SHARE - The Advisory helps people building in New Zealand compare construction lenders, structure the loan through the build and set up long-term lending on completion. Learn more about our new build lending advice, or contact an adviser to talk through your project.
Conclusion
A new build home loan in NZ rewards good preparation. Understand how progress payments work, cost the whole project, keep a contingency, and make the most of the lending rule exemptions without stretching your budget. Communicate early with your lender and builder when something changes, and plan the move to long-term lending before the keys are handed over.
Frequently Asked Questions
How much deposit do I need for a new build in NZ?
New build lending is exempt from the Reserve Bank's LVR restrictions, so some lenders accept a smaller deposit than for an existing home. The amount still depends on the lender, the project and your finances.
How are construction loan funds released?
Under a typical build contract, the lender pays the builder in stages as progress claims are made, often after an inspection or valuer's report. Turnkey contracts usually require most of the payment at completion.
Can I use KiwiSaver to build my first home?
Often, yes. Eligible first home buyers can usually use KiwiSaver towards land to build on, a house-and-land package or an off-the-plan home, but generally not to build on land they already own.
When do repayments start on a construction loan?
You usually pay interest on the amount drawn during the build, then principal and interest repayments once the home is complete and the loan is restructured.
What happens if building costs go up?
Tell your lender promptly and provide updated quotes and variations. Extra lending is not automatic and may need a new valuation or affordability check, so a contingency fund is important.
What protections do I have when building a home in NZ?
For work of $30,000 or more including GST, you must have a written contract and receive a disclosure statement and checklist. There is also a 12-month defect repair period and implied warranties that apply for 10 years.